

The Myth of the Free Ride
“When I no longer have to travel to the library but can download a book for free without leaving my den, that’s the end of book publishing.”
This mantra repeated with semi-religious conviction across trade publishing management contains a grain of truth. I do download library ebooks. That said, we are not at “the end” just yet. Not unless trade publishers insist on pricing themselves out of the market.
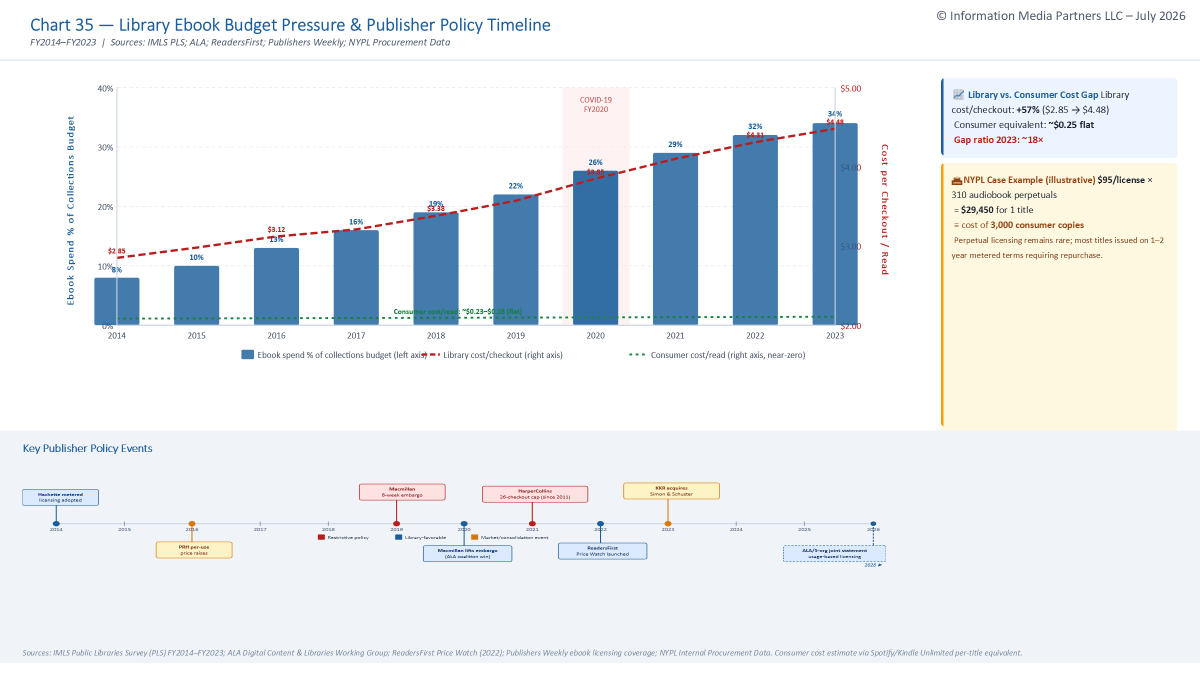
For more than a decade, trade publishers pushed a consistent narrative: library patrons are freeloading on ebooks, and unrestricted digital lending has/can/will cannibalize consumer sales. It’s a tidy disaster scenario but not supported by data.
What the data does show is an industry where consumer ebook revenue has been declining for structural reasons since 2014 — reasons that have nothing to do with library circulation. Audio books and Kindle Unlimited have more to answer for in this regard. Meanwhile, the prevailing digital licensing architecture effectively taxes library patrons for accessing a public service and pushes library budgets past the breaking point. Correlation has been conveniently mistaken for causation: It’s time to stop hyperventilating and consider reality.
Key Data: Digital Lending & Publisher Economics
+410% — Growth in library digital circulation, FY2014–FY2023 (128M → 652M), while consumer ebook revenue fell ~29%.
+17.3% — Annual library license price increase for HarperCollins titles (ReadersFirst Price Watch, 2022–2026).
34% → 15% — Decline in popular titles available on perpetual access (2019 → 2024). A deliberate structural shift.
Speaking of Causes
The trend lines move in opposite directions. If library digital lending were suppressing consumer ebook sales, we’d expect ebook revenue to fall because library circ rises. Instead, ebook revenue declines for reasons unrelated to libraries — including Amazon price negotiations, the rise of audiobooks, and format substitution.
And the discovery effect matters: patrons who first encounter ebooks through libraries often become future ebook buyers. This is well documented in academic literature. The “libraries kill sales” narrative is not.
Tickle Me Kindle
One obvious explanation for ebook revenue decline is that there’s a better deal for consumers available. Kindle Unlimited launched at $9.99/month (now $12.99) and offers unlimited access to millions of titles including vast quantities of commercially published fiction and romance, which are historically the strongest performing ebook genres. This suggest that substitution is far more likely happening here than at the library.
Add to that:
Audible Premium Plus and other unlimited audio models.
A massive surge in self-published and indie ebooks, priced at $0.99–$2.99, often from prolific authors with loyal followings.
These are the structural market forces compressing AAP-reported ebook revenue. Not libraries.
No peer-reviewed study in economics or library science has ever established a causal link between library digital lending and consumer ebook sales decline. The closest thing is publisher-commissioned internal analysis that has never been publicly released for methodological review. In other words: a fairy tale, not a finding.
Pay for Promotion
Library pricing realities are well documented. The dominant model for popular trade titles is metered access — a license that expires after a set number of checkouts or a fixed time period. Print books don’t expire - at least until they wear out. Digital licenses do.
Compared to consumer Kindle retail pricing (~$14), library ebook license multipliers are:
Penguin Random House — ~$60 (4.3×)
HarperCollins — ~$85 (6.1×)
Simon & Schuster — ~$65 (4.6×)
Hachette — ~$68 (4.9×)
Macmillan — ~$62 (4.4×)
And the annualized price increases (2022–2026):
HarperCollins — +17.3%
Hachette — +13.1%
Macmillan — +11.6%
A 17.3% annual increase is not inflation. It’s economic extraction from institutions which cannot take a pass on popular content without community blowback. Libraries cannot substitute. For bestselling titles, there is no alternative product.
The collapse of perpetual access compounds the problem. In 2019, 34% of popular titles were available on perpetual licenses. By 2024, 15%. Publishers are systematically removing ownership options and replacing them with expiring licenses. Libraries that once built collections now rent them. (Subscription models are not inherently bad but here it is all or nothing).
Model Warfare
Libraries have always sought partnership with publishers. What they’ve received is a beat down:
HarperCollins Publishers, offering 26-checkout licenses (about 1 year) on eBooks at an average of $28.39.
Penguin Random House, offering 24-month licenses on eBooks at an average of $55.00.
Macmillan Publishers, offering 24-month licenses on eBooks at an average of $60.00.
Simon & Schuster, offering 24-month licenses on eBooks at an average of $61.44 and on eAudio at an average of $78.99
Hachette Book Group, offering 24-month licenses on eBooks at an average of $68.25 and on eAudio at an average of $65.00.
(ReadersFirst Price Watch (2022) exposing price increases previously hidden from public view).
The data does not support a pricing strategy designed to reduce access in order to force retail purchases. Restrictive library pricing has not produced a retail uplift. It has produced constrained library budgets which will almost certainly result in narrow and shallow library collections. Libraries will have to forgo repurchasing recent front list and replacing back list only so they can afford new titles. Unhappy patrons have also caught the attention of legislators. Multiple bills modeled on Maryland’s Digital Content Act are emerging, though constitutional challenges remain likely. (The Maryland bill was ruled unconstitutional).
It is unfortunate that this is the state of the relationship and a fundamental question is unavoidable:
What does it mean to be a public library in a digital environment if your primary suppliers do not agree on the purpose, role, or business model of public access?
Digital lending has surged over 400% in a decade. Just like your old manager who mistakes decisiveness for competence, the industry’s claim that libraries hurt ebook sales mistakes correlation for causation. The real drivers are the structural shift toward audiobooks, subscription models, and indie publishing — not public digital circulation. Instead of weaponizing metered licensing, publishers should confront the market reality they actually face.
This is one of a series of posts on the current state of the US library market
See the earlier posts for the intro to the series.
Full Library Presentation 2014 - 2023
Michael Cairns is a senior publishing executive and consultant. He can be reached at michael. cairns @ outlook.com or 908 938 4889