

$14.8 billion in annual public library revenue sounds like a lot of money. And it is. Communities across the United States are funding their libraries at high levels, frequently passing local ballot measures, and authorizing more capital investment than at any point in the modern public library era. Yet, the aggregate figures paper over the fragility of the market below the surface. A decade of IMLS Public Libraries Survey data actually shows a sector that has grown nominally but has at the same time become more structurally dependent on a single revenue source, more exposed to the cost pressures of digital collections, and more quietly abandoned by state governments that once carried a more meaningful share of the load. If that’s not all, there’s also a resource problem with a workforce struggling to replace aging staff with newly qualified candidates.
Key Data — Post 1: Finances & Fiscal Context
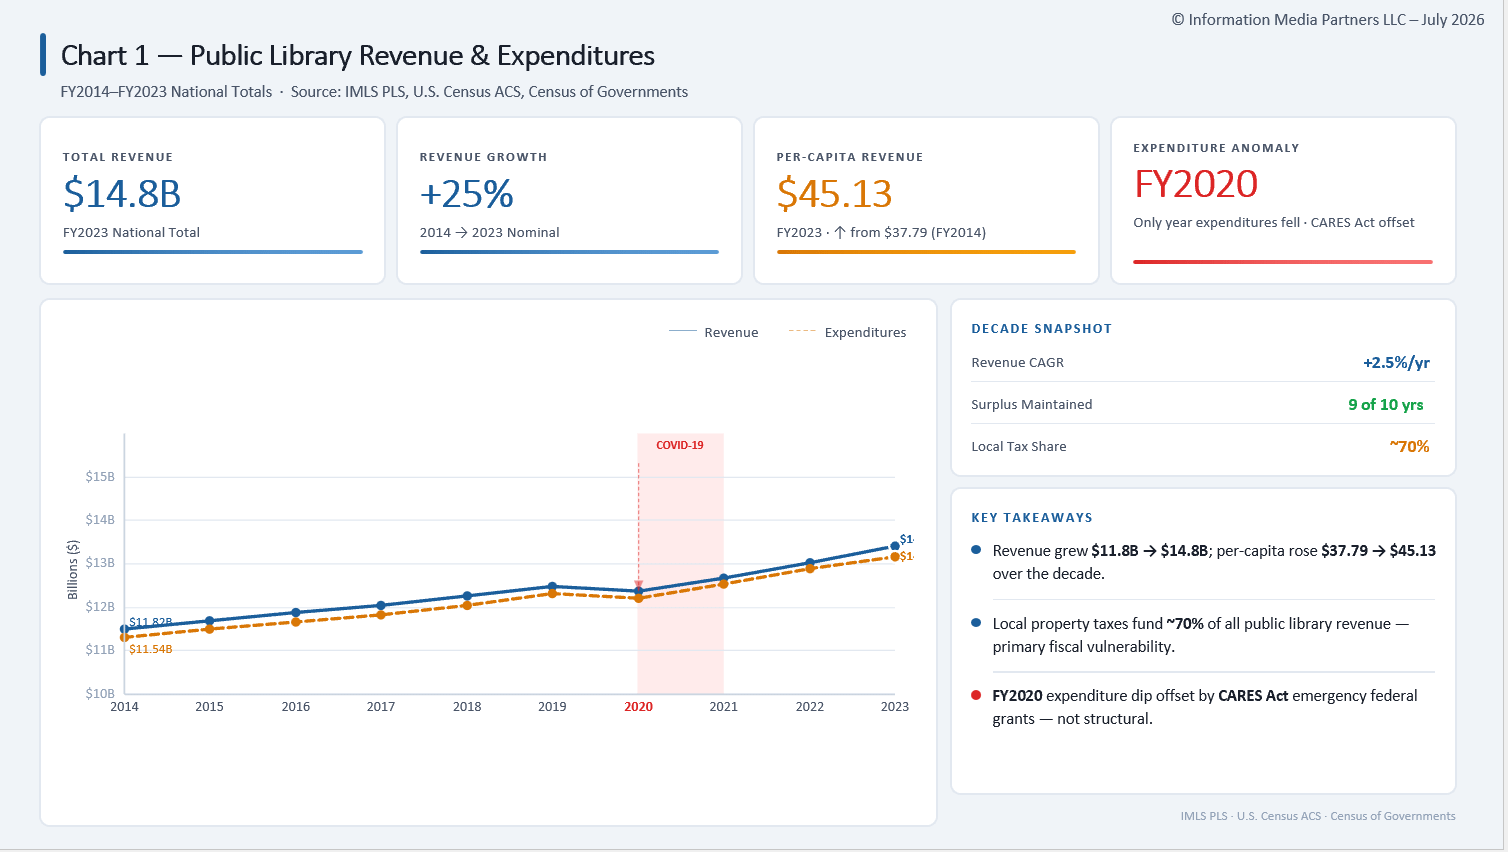
+25.1% Nominal growth in total public library operating revenue, FY2014–FY2023 ($11.82B → $14.78B)
15.4% State share of combined state+local library funding in FY2023, down from 18.4% in FY2014
$1.68B Dollar value of library ballot measures authorized in FY2023 — a record high
Nominal Growth Isn’t Real Growth
Total operating revenue grew from $11.82 billion in FY2014 to $14.78 billion in FY2023 — a nominal increase of 25.1%. Per-capita revenue rose from $37.79 to $45.13, and per-capita expenditures tracked closely, moving from $36.89 to $44.03. It looks like the library is keeping pace, but against cumulative CPI over the same period — roughly 30–32% — real purchasing power has eroded. The sector is running faster to stay in the same place, and in some budget categories losing ground despite the growing nominal spending increase.
The 70% Problem
It is well known that the core structural issue in public library finance is that approximately 70% of public library operating revenue comes from local property taxes. This structure survives on the assumption that local property values will be stable, growing, and sufficient. When local housing markets soften, library budgets follow. When a recession hits and property tax collections lag (often by 12–18 months due to assessment cycles), library directors face mid-cycle cuts with almost no reserve cushion. When a tax levy fails — and the margin in many communities is thin — there is no plan B.
This isn’t a new dynamic, but options are limited. Libraries that haven’t built reserves, pursued alternative revenue streams, or deepened their relationships with municipal and county budget processes are exposed in ways they may not fully appreciate until a correction arrives.
States Are Pulling Back — And Almost Nobody Is Saying It Plainly
State aid to libraries struggles to keep up with inflation. On paper, state appropriations to public libraries are higher in FY2023 than they were in FY2014. But in real, inflation-adjusted terms, state aid declined approximately 3% over the period. More telling: the state share of combined state-plus-local library funding fell from 18.4% in FY2014 to 15.4% in FY2023. That three-percentage-point shift represents a quiet but meaningful retrenchment in the state commitment to public library funding — one that has been obscured by the nominal growth in the overall funding base.
Most library directors and trustees don’t realize how significant this erosion has been, because the nominal numbers look fine. State aid is up in dollar terms. That makes it easy to miss that local governments are increasingly carrying a burden that states once shared more substantially. The practical consequence: libraries in communities with strong local tax bases are insulated from this shift; libraries in economically distressed communities — where local tax capacity is weakest and state aid matters most — are the ones being quietly squeezed.
The ballot measure story is genuinely encouraging. Pass rates climbed from 76.1% in FY2014 to 81.8% in FY2023. The dollar value authorized hit a record $1.68 billion in FY2023. Communities demonstrably value their libraries — that signal from voters is consistent and strong. But ballot measures are geographically uneven, and dependent on staff capacity and political organizing to run campaigns. A small rural library system with one director and two part-time staff does not have the bandwidth to mount a ballot campaign every levy cycle. This is no less true at an overburdened inner city library. The communities most reliant on state aid are often the least positioned to replace it through local ballot initiative.
Meanwhile, both of the largest expenditure categories are under upward pressure simultaneously. Personnel costs are rising as wage compression reverses, union obligations expand, and the broader labor market forces salary adjustments that were long overdue. At the same time, digital collection costs — e-book licensing, database subscriptions — have grown as a share of total budgets in ways that will be detailed in later posts. Academic libraries face this even more acutely: journal subscription price inflation averaged 5–7% annually across the decade, consistently above CPI and consistently above library budget growth. The dual cost squeeze is real, and the relief valve — state aid — is quietly closing.
The next 2-year outlook is unsettling: Property tax growth is slowing in many markets as the post-pandemic housing surge cools. Several states face structural deficits in their FY2026–27 budget cycles, and when states cut, libraries are typically immediately impacted. And the cost pressure from digital collections is not abating — it is, if anything, accelerating, as I’ll document in later posts. Libraries should be conducting frank conversations with state legislatures about real-dollar commitments — not nominal ones — before the erosion becomes visible in service cuts. That conversation needs to start now, because by the time the cuts are visible, the political window to reverse them will have narrowed considerably.
Look for the next post in this series showing books are the least of what a library offers its community. See the earlier post for the intro to the series.
Full Library Presentation 2014 - 2023
Michael Cairns is a senior publishing executive and consultant. He can be reached at michael. cairns @ outlook.com or 908 938 4889